Showing posts with label United States. Show all posts

Sunday, January 25, 2026

Wildfire smoke and outdoor recreation welfare losses

Wildfire smoke has surged across the western United States, and this paper quantifies the per-trip welfare loss when campers confront smoky conditions. Using millions of campground reservations merged with day-by-day satellite smoke plumes and PM data, the authors estimate that smoke reduces welfare by $107 per person per trip, with larger losses when smoke persists for consecutive days.  From a back-of-the-envelope scaling, they infer that ~21.5 million outdoor recreation visits in the West are affected annually, implying aggregate welfare losses of about $2.3 billion per year purely on the recreation side—separate from health costs.  Although many smoke studies emphasize morbidity and mortality, this one zeroes in on revealed-preference behavior at high frequency, exploiting sequential decision-making as campers cancel, rebook, or stick with reservations as smoke forecasts evolve, which helps isolate causality in a way rarely possible with coarser data.  Importantly, the $107 estimate is per person, so party size and trip length compound damages quickly; it also varies with consecutive-day exposure, indicating nonlinear disutility as air quality remains poor.

Methodologically, the study deploys a novel control-function approach to capture evolving information and sequential choice, then links those structural decisions to satellite-based smoke and pollution metrics at the site-day level.  The identification gains power from tens of millions of administrative reservations covering multiple states and seasons, allowing them to detect how campers reallocate across sites and dates when smoke intrudes.  The welfare measures are based on standard discrete-choice valuation, but the key novelty is high-frequency exposure information, which captures the fact that smoke impacts are episodic and often abrupt, unlike the relatively smoother variation in annual PM averages.  The results imply that short-run recreation damages alone—again, ~$2.3 billion/year—are already material for public-lands management and visitor communication strategies, even before accounting for medical spending, lost productivity, or longer-run changes in park demand.

Contextually, this article sits alongside a growing literature showing that wildfire smoke now accounts for up to half of PM in some western locales, amplifying the urgency of smoke-specific preparedness and messaging on public lands.  The authors’ results also dovetail with evidence that recent fire seasons have been hotter, longer, and more severe, which suggests that $107 per-person trip losses may be a floor in extreme years.  Policymakers considering campground closure thresholds, reservation refund policies, or smoke-forecast integration into recreation apps can use the per-trip metric as a transparent, transferable input for cost-benefit analysis.  For example, the paper’s consecutive-day effect implies higher returns to rapid response (e.g., targeted closures or fee waivers) once forecasts indicate multi-day smoke. 


Jacob Gellman, Margaret Walls, and Matthew Wibbenmeyer. “Welfare Losses from Wildfire Smoke: Evidence from Daily Outdoor Recreation Data.” Journal of Environmental Economics and Management 132 (March 2025). https://www.sciencedirect.com/science/article/pii/S0095069625000506


Monday, May 22, 2023

EPA and State of New Jersey Propose Settlement with Bank of America for Monmouth County, NJ Superfund Site Cleanup

On May 15, 2023 the U.S. Environmental Protection Agency (EPA) announced a proposed settlement with Bank of America to address the White Swan Cleaners/Sun Cleaners Area Groundwater Contamination Superfund Site in Wall Township, Monmouth County, New Jersey. Under the proposed agreement, Bank of America, the current owner of the White Swan property, will be required to fund and perform vapor intrusion and groundwater cleanup work at an estimated cost of $29 million.

"With this settlement EPA is holding Bank of America accountable for its share of the cleanup at the White Swan site," said Regional Administrator Lisa F. Garcia. " After years of investigation and cleanup efforts, this is a significant step towards resolving the contamination issues at the site for the benefit of the community, the environment, and public health."

“The New Jersey Department of Environmental Protection and U.S. Environmental Protection Agency are committed to protecting the health of those who live and work in the vicinity of the White Swan Cleaners/Sun Cleaners site,” New Jersey Commissioner of Environmental Protection Shawn M. LaTourette said. “We have partnered together to test indoor air at hundreds of business and residential properties and installed ventilation systems on dozens with vapor intrusion concerns. This settlement with Bank of America ensures that long term cleanup, including remediation of contaminated groundwater and future vapor mitigation work, will be funded by the responsible party, not by the taxpayers.”

Bank of America became legally responsible for the site when it bought the White Swan property through a series of bank mergers and acquisitions in 2004.

Bank of America also will reimburse EPA for certain aspects of its cleanup work, paying $10.8 million, and pay up to $1.5 million for future EPA oversight costs. As part of the agreement, Bank of America will construct and then run the groundwater pump and treatment system for four years to capture and clean the most highly contaminated groundwater at the site.

The company will pay up to a total of $6.5 million to the State of New Jersey to settle its liability for cleanup and removal costs, to voluntarily resolve its liability for natural resource damages (NRD), and to address long-term operational needs of the treatment system. This amount includes $3.7 million for cleanup costs and $2.8 million set aside in an escrow account for any future groundwater system operation and maintenance or added vapor intrusion work needed after the State takes over the cleanup.

Vapor intrusion occurs when volatile organic compounds (VOCs) from contaminated soil and groundwater seep into buildings, potentially exposing occupants to harmful chemicals. EPA has found that the former dry-cleaning operations of White Swan Cleaners and Sun Cleaners were the sources of soil and groundwater contamination. VOCs from the contamination can easily evaporate into the air and cause health hazards. EPA added the site to the National Priorities List (NPL) in 2004. In the course of the cleanup, EPA and the New Jersey Department of Environmental Protection (NJDEP) have installed several indoor air ventilation systems after conducting indoor air testing on residential and commercial properties. In 2018, EPA also oversaw Bank of America’s removal of contaminated soil from the White Swan property. Cleanup of the Sun property, which is not related to the White Swan property, is being funded by EPA.

https://www.epa.gov/vaporintrusion/what-vapor-intrusion

The proposed consent decree, which has been lodged in the U.S. Federal District Court of New Jersey, is subject to a 60-day comment period. The Department of Justice and EPA will evaluate the comments and decide whether to proceed and then, if appropriate, seek final approval by the court.

For more information, to view the proposed consent decree and to give comments, please visit: https://www.justice.gov/enrd/consent-decrees

Thursday, May 11, 2023

Health, air pollution, and location choice

Abstract:
This paper provides evidence that air-pollution-related health conditions change how households evaluate clean air and, as a result, incentivize them to relocate to locations with better air quality. The evidence implies that naive estimations of the adverse effect of air pollution on health are biased, as people sort on air quality differently depending on their health. [The author employs] a spatial-equilibrium model in which households choose a county to live in based on county-level characteristics including air pollution. Using National Longitudinal Survey of Youth data, [the author creates] a panel tracking respondents’ respiratory health shocks and county-level location for over three decades. The estimates from a multinomial mixed logit model support the hypothesis that households move to cleaner-air locations after an adult is diagnosed with asthma. [Siyu Pan finds] that households react more strongly to an asthma diagnosis for an adult than to a child’s diagnosis. The estimated median increase in marginal willingness to pay for a one-unit reduction in Air Quality Index after a diagnosis of adult-onset asthma is $157–$830 (in constant 1982–84 dollars).
Air Quality by County

by Siyu Pan, Department of Economics, Georgia State University, 55 Park Place, Atlanta, GA 30302, United States of America and The W. A. Franke College of Business, Northern Arizona University, 
Journal of Environmental Economics and Management https://www.sciencedirect.com/journal/journal-of-environmental-economics-and-management via Elsevier Science Direct www.ScienceDirect.com
Volume 119; May, 2023; 102794, Available online 22 February 2023

Wednesday, May 10, 2023

New Vehicle Standards Will Produce Enormous Benefits for Consumers and the Climate

Updated pollution standards for cars and trucks will cut fuel costs and avoid up to a trillion dollars’ worth of climate-related damages

One April 13, 2023, the Environmental Protection Agency proposed new vehicle standards that will significantly reduce emissions of greenhouse gases and other criteria pollutants from the transportation sector. EPA’s multipollutant standards for light- and medium-duty vehicles sold in Model Years 2027 through 2032 will both reduce pollution and save consumers money—generating substantial societal benefits in the process.

Meredith Hankins, Senior Attorney at the Institute for Policy Integrity at NYU School of Law, issued the following statement: “EPA has a long history of using ambitious emission standards to protect public health, and today’s proposal adds to that history. The proposed standards for passenger vehicles are estimated to result in up to $1 trillion dollars in climate benefits, $280 billion in health benefits from reducing other pollution, and up to $770 billion in avoided fuel costs for consumers. This proposal, and the companion proposal for heavy-duty vehicles, recognize automotive manufacturers’ own commitments to electrify their fleets and build on Congressional incentives in the Inflation Reduction Act. EPA’s proposals represent an achievable path toward increasing the market-share of zero-emission vehicles.”

Relatedly, the Institute for Policy Integrity filed an Amicus Brief Defending NHTSA Corporate Average Fuel Economy Standards on April 4, 2023.  They noted that in May 2022, the National Highway Traffic Safety Administration (NHTSA) finalized a rule to increase its corporate average fuel economy (CAFE) standards for passenger cars and light trucks for model years 2024–2026. A group of fuel and petrochemical manufacturers and states challenged the standards in the U.S. Court of Appeals for the D.C. Circuit, arguing primarily that the Energy Policy and Conservation Act bars NHTSA from including electric vehicles in the analytical baseline for the new standards. Their amicus brief explains that longstanding administrative guidance and case law direct agencies to develop baselines that reflect their best assessment of the real world absent any new agency action. In the context of this rulemaking, that guidance and case law required NHTSA to project how many and what kinds of vehicles—including electric (and plug-in hybrid electric) vehicles—would be built and sold if it did not issue new CAFE standards, which is what NHTSA did here. Their amicus brief also explains that NHTSA has consistently prepared baselines for prior CAFE standards in this manner.

The Institute for Policy Integrity at New York University School of Law, a non-partisan think tank dedicated to improving the quality of government decisionmaking. The institute produces original scholarly research in the fields of economics, law, and regulatory policy; and advocates for reform before courts, legislatures, and executive agencies. https://policyintegrity.org
Press Release dated April 13, 2023
Also see
Multi-Pollutant Emissions Standards for Model Years 2027 and Later Light-Duty and Medium-Duty Vehicles
A Proposed Rule by the Environmental Protection Agency on 05/05/2023
in the Federal Register

Regional Greenhouse Gas Initiative Would Lower Pennsylvania Emissions, Add to State Revenues, and Have Little to No Impact on Electricity Rates

A new report analyzes the expected impact on Pennsylvania emissions, power generation, revenue, and jobs, offering six central conclusions.  

In 2022, despite fierce opposition, Pennsylvania joined the Regional Greenhouse Gas Initiative (RGGI), a cap-and-trade program designed to reduce carbon emissions from Northeastern and Mid-Atlantic power plants. Ongoing lawsuits have so far prevented the program from going into effect. But what impact would RGGI have on Pennsylvania if the program passes muster?

Researchers at the Kleinman Center for Energy Policy at the University of Pennsylvania and Resources for the Future (RFF) joined forces to find out.  A new report released by the two institutions analyzes the expected impact on Pennsylvania emissions, power generation, revenue, and jobs, offering six central conclusions:  

Joining RGGI reduces Pennsylvania’s electricity sector emissions to 84 percent below 2020 levels in 2030. Without RGGI, the state’s electricity sector emissions would be 52-49 percent below 2020 levels in 2030.

Combined Economic Effects in Pennsylvania


Emissions reductions are achieved with small or negative changes in retail electricity prices. Low allowance prices translate into a small increase (1 percent) in Pennsylvania’s retail electricity prices in 2030 under an annual 3-percent declining emissions cap. When the cap declines to zero by 2040, retail prices see a small decrease (-0.6 percent).  

Joining RGGI decreases coal generation and increases renewable generation in Pennsylvania. Joining RGGI causes coal generation and—to a lesser extent—gas generation to fall in Pennsylvania. Wind and solar capacity and generation increase. 

Joining RGGI decreases Pennsylvania exports slightly, but the state remains a major regional electricity exporter across all scenarios. The increase in renewable generation is not as large as the decrease in fossil generation, leading to a reduction in exports.  

Pennsylvania gains substantial revenue from joining RGGI. While allowance prices are low in 2030 if Pennsylvania joins RGGI, the state still gains $101 to $148 million from the auction of emissions allowances in that year—much of it from allowances sold to generators in other states.

Joining RGGI is unlikely to impact overall employment in the state. Pennsylvania would have the opportunity to use some of the program revenue to benefit communities impacted by the phaseout of coal. 

The team used RFF’s Haiku electricity model to see what would happen if Pennsylvania joined—or did not join—RGGI under two emissions scenarios: one in which RGGI’s emissions “cap” falls 3 percent per year, and one in which the RGGI cap falls at 3 percent per year through 2026 and to zero in 2040.  

Thursday, November 12, 2020

Monetising the savings of remotely sensed data and information in Burn Area Emergency Response (BAER) wildfire assessment

Abstract
We used a value of information approach to demonstrate the cost-effectiveness of using satellite imagery as part of the Burn Area Emergency Response (BAER), a US federal program that identifies imminent post-wildfire threats to human life and safety, property and critical natural or cultural resources. We compared the costs associated with producing a Burn Area Reflectance Classification map and implementing a BAER when imagery from satellites (either Landsat or a commercial satellite) was available to when the response team relied on information collected solely by aerial reconnaissance. The case study included two evaluations with and without Burn Area Reflectance Classification products: (a) savings of up to US$51 000 for the Elk Complex wildfire incident request and (b) savings of a multi-incident map production program. Landsat is the most cost-effective way to input burn severity information into the BAER program, with savings of up to US$35 million over a 5-year period.
by Richard Bernknopf, Yusuke Kuwayama, Reily Gibson, Jessica Blakely, Bethany Mabee, T.J. Clifford, Brad Quayle, Justin Epting, Terry Hardy, and David Goodrich
International Journal of Wildland Fire - https://www.publish.csiro.au/wf
Published online: 22 October 2020 

Wednesday, January 8, 2020

Moral Hazard, Wildfires, and the Economic Incidence of Natural Disasters

Abstract:
This study measures the degree to which large public expenditures on wildfire protection subsidize development in harm's way. Using administrative firefighting data, we calculate geographically-differentiated implicit subsidies to homeowners throughout the western USA. We first examine how the presence of homes affects firefighting expenditures. These results are used to reconstruct the implied historical cost of protecting each home and to perform an actuarial calculation of expected future protection cost. The expected net present value of this subsidy can exceed 20% of a home's value. It increases with fire risk and decreases surprisingly steeply with development density. A simple model is used to explore effects on expansion of developed areas, density, and private risk-reducing investments. These results demonstrate how policy and institutions influence the costs imposed by a changing climate.
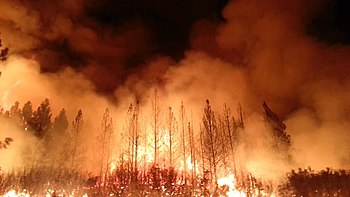
The Rim Fire burned more than 250,000 acres (1,000 km2) of forest near Yosemite National Park, in 2013https://en.wikipedia.org/wiki/Wildfire
...
During 1985–2017 total wildfire property damages in the United States were $51 billion, while direct firefighting costs for federal agencies alone totaled $43 billion.
...
A sample of homes including all 8.6 million homes in the western US located near areas of wildland vegetation (44% of all western US residential homes, condos, and apartments)....The range of historical protection costs is large. The average net present value ranges from a few hundred dollars per home for the lowest-cost cells to almost $100,000 per home in the highest-cost cells.
...
Using the “suppression only” measure, 50% of WUI homes have expected protection costs under $500, while the highest-risk homes have costs that are much larger. Five percent of homes have expected costs exceeding $3,800. One percent of homes have expected protection costs exceeding $12,700. Using the “suppression plus” measure results in higher costs. The 95th and 99th percentiles of this distribution are about twice as high as for the “suppression only” measure.
...
In 2014, California began requiring homeowners in the Cal Fire protection area to pay an equal annual fee of about $150 per year. The fee proved unpopular among homeowners and was suspended in 2017. This study shows that such a fee would need to be much more geographically differentiated in order to correct incentives (as opposed to simply raising revenue). Another lesson from this study is that exempting owners of existing homes could increase the political acceptability of such a policy without reducing its effectiveness, since the protection costs we estimate are not generally high enough to justify abandonment of existing homes. An alternative would be to assign firefighting costs to local governments, which would recover them through property taxes or other measures. This approach would incentivize cities and counties to consider fire protection costs in zoning, land use, and building codes/


https://www.nber.org/papers/w26550
by Patrick Baylis and Judson Boomhower
National Bureau of Economic Research (NBER) www.NBER.org
NBER Working Paper No. 26550; Issued in December 2019

Looking Back at Fifty Years of the Clean Air Act - After major expansion in 1970, the Clean Air Act led to substantial emissions reductions and health improvements—as well as some unintended consequences.

Abstract
Since 1970, transportation, power generation, and manufacturing have dramatically transformed as air pollutant emissions fell significantly. To evaluate the causal impacts of the Clean Air Act on these changes, we synthesize and review retrospective analyses of air quality regulations. The geographic heterogeneity in regulatory stringency common to many regulations has important implications for emissions, public health, compliance costs, and employment. Cap-and-trade programs have delivered greater emission reductions at lower cost than conventional regulatory mandates, but policy practice has fallen short of the cost-effective ideal. Implementing regulations in imperfectly competitive markets have also influenced the Clean Air Act’s benefits and costs.
  • Spatially varying regulations can impose substantial costs on local economies.
  • Current applications of market-based mechanisms may fall short of cost-saving expectations.
  • Varying fuel content regulations across the United States may impose unnecessary costs on consumers in separated markets.
  • Regulatory flexibility for fuel content rules doesn’t always yield cost-effective results.
  • Unanticipated costs arising from overly optimistic technology projections are an important issue in the design of renewable fuel requirements.
The SO2 program has been subject to extensive research, with a number of papers focusing on the early years (such as Carlson et al. 2000 and Ellerman et al. 2000) and some recent synthesis and review papers which combine ex-ante and ex-post papers (such as Schmalensee and Stavins 2013). The ex-ante analyses all suggest large cost savings based on a comparison of the least cost solution of achieving the cap to the command-and-control uniform performance standard case. Carlson et al. (2000) note that this cost reduction reflected dramatic declines in their estimated marginal abatement cost functions for sulfur dioxide emissions resulting from changes in technology and low-sulfur coal prices over 1985-1995.

The only true ex post study of the program’s benefits and costs is by Chan et al. (2018), which finds much smaller cost savings than predicted ex ante. In part, this is the result of decisions of several power plants—in concert with their state public utility commissions—to install scrubbers rather than comply by purchasing allowances and/or using low sulfur coal, a decision that Chan et al. estimate increased annual compliance costs by nearly $100 million. Focusing on 2002 as a Phase II year before the transition to a period of regulatory uncertainty and using a mixed logit model of the firm’s compliance decision, the authors find that the SO2 program reduced compliance costs by about $200 million (1995$) and increased public health benefits by roughly $170 million. Chan et al. examine a performance standard that delivers the same aggregate emission outcome as the Acid Rain Program in 2002, which had much higher emissions than the cap due to use of banked allowances. Thus, the cost-savings of the two instruments may be smaller than they would have been under the statutory cap for 2002. Chan et al. also find that the prevailing pattern of allowance trading— from western generating units in sparsely populated areas to eastern generating units in more densely populated areas—increases public health damages by about $2 billion relative to a no-trade counterfactual.
...
The Chan et al. paper builds on the insights in Muller and Mendelsohn (2009), which illustrated through an integrated assessment model how the location of an emission source relative to a downwind population could dramatically affect the monetized damages of a ton of sulfur dioxide emitted at that source. In their counterfactual analyses, Muller and Mendelsohn estimated that trading ratios, based on the relative damages associated with a ton of emissions for a pair of locations, could improve social welfare by nearly $1 billion per year compared to the ton-for-ton trading in the SO2 program as implemented. However, such differentiation in cap-and-trade implementation raises questions about administrative feasibility and accuracy in estimating ratios, especially in the presence of a complicated atmospheric chemistry that could induce negative ratios for NOx (Fraas and Lutter 2012). 
...
While overall coal prices fell during the latter half of the 1990’s, Busse and Keohane found that delivered prices rose for plants covered by Phase I of the SO2 cap-and-trade program relative to those still operating under command-and-control regulation, and prices rose more at plants near a low-sulfur coal source. Overall, they estimate that railroads enjoyed an increase in annual producer surplus of more than $40 million, which represented about 15 percent of the economic surplus created by the cap-andtrade program....

Saturday, September 29, 2018

SAFE Issue Brief Highlights Military Cost of Protecting Global Oil Supply

According to the calculations of the Environmental Protection Agency (EPA) and the National Highway Traffic Safety Administration (NHTSA), the cost to the United States of defending the global oil supply is zero. This zero-cost estimate comes from the methodology used by the U.S. government budgets for national defense. Since it is difficult to assign a cost to the oil protection mission—and since the Department of Defense (DoD) would realize no savings if this mission were not pursued—EPA and NHTSA conclude that it is pointless to assign any value above zero for this activity. This approach fails to account for the large opportunity costs of protecting the global oil supply.

To more accurately assess the military cost to the U.S. of protecting global oil supplies—and therefore understanding the military cost/benefit of the Fuel Economy Standards (FES) program—SAFE conducted an extensive review of the existing literature that analyzes the military cost of U.S. oil dependence. In addition, SAFE carried out a series of interviews with military members of its Energy Security Leadership Council (ESLC) as well as other leading experts in this field.
  • At minimum, approximately $81 billion per year is spent by the U.S. military protecting global oil supplies. This is approximately 16 percent of recent DoD base budgets. Spread out over the 19.8 million barrels of oil consumed daily in the U.S. in 2017, the implicit subsidy for all petroleum consumers is approximately $11.25 per barrel of crude oil, or $0.28 per gallon. A more extensive estimate by two highly-regarded economists suggests the costs could be greater than $30 per barrel, or over $0.70 per gallon.
  • America’s dependence on oil as the primary transportation fuel has costs beyond those directly shown at the gas pump. SAFE and its ESLC strongly believe based on first hand experience that the military cost of oil dependence is substantially greater than zero, and argue that a cost of at least $0.28 per gallon should be used by EPA and NHTSA in their military cost/benefit analysis for the FES program.
  • Reducing oil use in the transportation sector allows for the possibility of shifting U.S. military priorities toward more critical strategic threats. “If we reduced our oil consumption by half, [the U.S. military] would act differently,” says ESLC member Admiral Dennis C. Blair, the former Director of National Intelligence and Commander in Chief of the U.S. Pacific Command. General Duncan McNabb, the former commander of the U.S. Transportation Command and also a member of SAFE’s ESLC stated: “If we can reduce our dependence on oil, we could reduce our presence in the Gulf and use the funds for other critical military priorities, like cybersecurity or hypersonic weapons. The same funds could support different security priorities. We would make different choices, that would make us safer and more secure.”
The full report can be found here.

Securing America's Future Energy https://secureenergy.org
Press Release dated September 20, 2018
via/hat tip "We now have a dollar value for one of oil’s biggest subsidies - Defending the oil supply costs a lot of money" By David Roberts@drvox  https://www.vox.com/energy-and-environment/2018/9/21/17885832/oil-subsidies-military-protection-supplies-safe

Saturday, September 8, 2018

In 2015, peripheral devices consumed nearly as much electricity as televisions

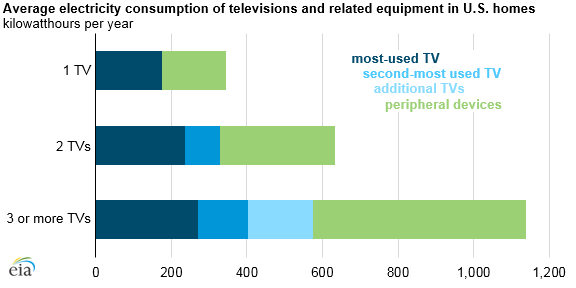
Results from EIA’s 2015 Residential Energy Consumption Survey (RECS) show that televisions and related peripheral devices—such as digital video recorders (DVRs), video game consoles, and streaming devices—consumed 7% of the electricity used in American homes in 2015 and cost $103 per home per year to operate. Peripheral device consumption accounted for slightly less than half of this electricity consumption, collectively using almost as much energy as televisions.

average consumption of televisions and related equipment in U.S. homes

The new RECS data also provide insights into the consumption of the most-used and second-most-used TV in a home. RECS asks respondents detailed questions about their two most-used televisions, such as how many hours they are turned on, the size of the display, and the type of screen. This information informs the models used to estimate television consumption.

In homes with more than one TV, the most-used TV consumed more than twice as much electricity as the second-most used TV. In addition, energy consumption of the most-used TV was higher in homes that had more than one TV. In homes with more than one TV, the most-used TV tended to be larger and was turned on for more hours each day.

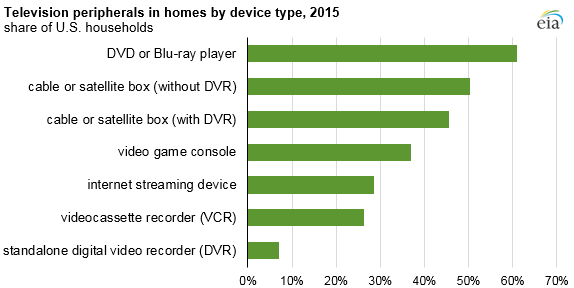
The RECS end-use category of televisions and related equipment aggregates the electricity consumption of televisions—which are found in 97% of American homes—with the electricity consumption of seven types of peripheral devices. Many of these devices may perform multiple functions, such as cable or satellite boxes that include a DVR or video game consoles that can connect to internet streaming services.
television peripherals in homes by device type
Of the devices surveyed, DVD and Blu-ray players were the most common, present in 61% of homes. Cable or satellite boxes without DVR capabilities were the second-most common, found in half of all homes. Separate DVRs were the least common, present in only 7% of homes.

The 2015 RECS was the first time the survey asked respondents about Internet streaming devices that allow users to view media from the Internet on their TV such as Roku and Apple TV; 29% of respondents reported having such a device. On average, homes with a television had a total of 3.9 peripheral devices, or 1.6 devices per TV.

Although they may perform the same functions, some peripheral devices can be much more energy efficient than others. For instance, internet-enabled smart TVs are the most efficient way to stream media compared with streaming devices or game consoles being used for the same purpose, according to analysis by the Environmental Protection Agency’s ENERGY STAR program.

Televisions and peripheral devices often consume energy even when they are not in active use. They draw power in standby mode, allowing them to receive a signal from a remote control, perform recording functions, and maintain internet connection.

ENERGY STAR-certified televisions are on average 27% more energy efficient than televisions that are not certified. Features such as highly efficient lighting technologies, default brightness settings less than the maximum, and automatic brightness control make televisions more energy efficient. One of the requirements to be ENERGY STAR-certified is that a television must consume 3 watts or less when in standby mode.

You can find more information on household energy consumption and expenditures in the RECS data tables and microdata file.

Principal contributor: Maggie Woodward
September 6, 2018


Tuesday, August 28, 2018

Report Confirms Wind Technology Advancements Continue to Drive Down Wind Energy Prices - Key findings indicate wind energy prices at all-time lows as wind turbines grow larger

Wind energy pricing remains attractive, according to an annual report released by the U.S. Department of Energy and prepared by Lawrence Berkeley National Laboratory (Berkeley Lab). At an average of around 2 cents per kilowatt-hour (kWh), prices offered by newly built wind projects in the United States are being driven lower by technology advancements and cost reductions.

“Wind energy prices ­– ­particularly in the central United States, and supported by federal tax incentives – remain at all-time lows, with utilities and corporate buyers selecting wind as a low-cost option,” said Berkeley Lab Senior Scientist Ryan Wiser of the Electricity Markets & Policy Group.

Key findings from the U.S. Department of Energy’s Wind Technologies Market Report include:

Wind power capacity additions continued at a rapid pace in 2017. Nationwide, wind power capacity additions equaled 7,017 megawatts (MW) in 2017, with $11 billion invested in new plants. Wind power constituted 25 percent of all U.S. generation capacity additions in 2017. Wind energy contributed 6.3 percent of the nation’s electricity supply, more than 10 percent of total electricity generation in 14 states, and more than 30 percent in four of those states (Iowa, Kansas, Oklahoma, and South Dakota).

Bigger turbines are enhancing wind project performance. The average generating capacity of newly installed wind turbines in the United States in 2017 was 2.32 MW, up 8 percent from the previous year and 224 percent since 1998-1999. The average rotor diameter in 2017 was 113 meters, a 4 percent increase over the previous year and a 135 percent boost over 1998-1999, while the average hub height in 2017 was 86 meters, up 4 percent from the previous year and 54 percent since 1998-1999. Permit applications to the Federal Aviation Administration suggest that still-taller turbines are on the way. Increased rotor diameters, in particular, have begun to dramatically increase wind project capacity factors. The average 2017 capacity factor among projects built from 2014 through 2016 was 42 percent, compared to an average of 31.5 percent among projects built from 2004 to 2011, and 23.5 percent among projects built from 1998 to 2001.

Low wind turbine pricing continues to push down installed project costs. Wind turbine equipment prices have fallen to $750-$950/kilowatt (kW), and these declines are pushing down project-level costs. The average installed cost of wind projects in 2017 was $1,610/kW, down $795/kW from the peak in 2009 and 2010.
Wind energy prices remain low. Lower installed project costs, along with improvements in capacity factors, are enabling aggressive wind power pricing. After topping out at 7 cents per kWh in 2009, the average levelized long-term price from wind power sales agreements has dropped to around 2 cents per kWh – though this nationwide average is dominated by projects that hail from the lowest-priced region, in the central United States. Recently signed wind energy contracts compare favorably to projections of the fuel costs of gas-fired generation. These low prices have spurred demand for wind energy from both traditional electric utilities and nonutility purchasers, such as corporations, universities, and municipalities.

The domestic supply chain for wind equipment is diverse. Wind sector employment reached a new high of 105,500 full-time workers at the end of 2017. For wind projects recently installed in the United States, domestically manufactured content is highest for nacelle assembly (more than 90 percent), towers (70 to 90 percent), and blades and hubs (50 to 70 percent). It is much lower (less than 20 percent) for most components internal to the turbine. Although there have been a number of manufacturing plant closures over the last decade, each of the three largest turbine suppliers serving the U.S. market – Vestas, General Electric Co., and Siemens Gamesa – has one or more domestic manufacturing facilities in operation.

The Department of Energy’s release on this study is available at energy.gov/windreport.

Berkeley Lab www.lbl.gov
Press Release dated August 23, 2018

Friday, August 25, 2017

National Renewable Energy Laboratory (NREL) Updates Baseline Cost and Performance Data for Electricity Generation Technologies

The Energy Department's National Renewable Energy Laboratory (NREL) has released the 2017 Annual Technology Baseline (ATB), updating a key source of reliable electricity generation technology cost and performance data used to support and inform electric sector analysis in the United States. Now in its third year, the ATB documents technology-specific information on a broad spectrum of electricity generation technologies, including wind, solar, geothermal, hydropower, biomass, coal, natural gas, and nuclear.
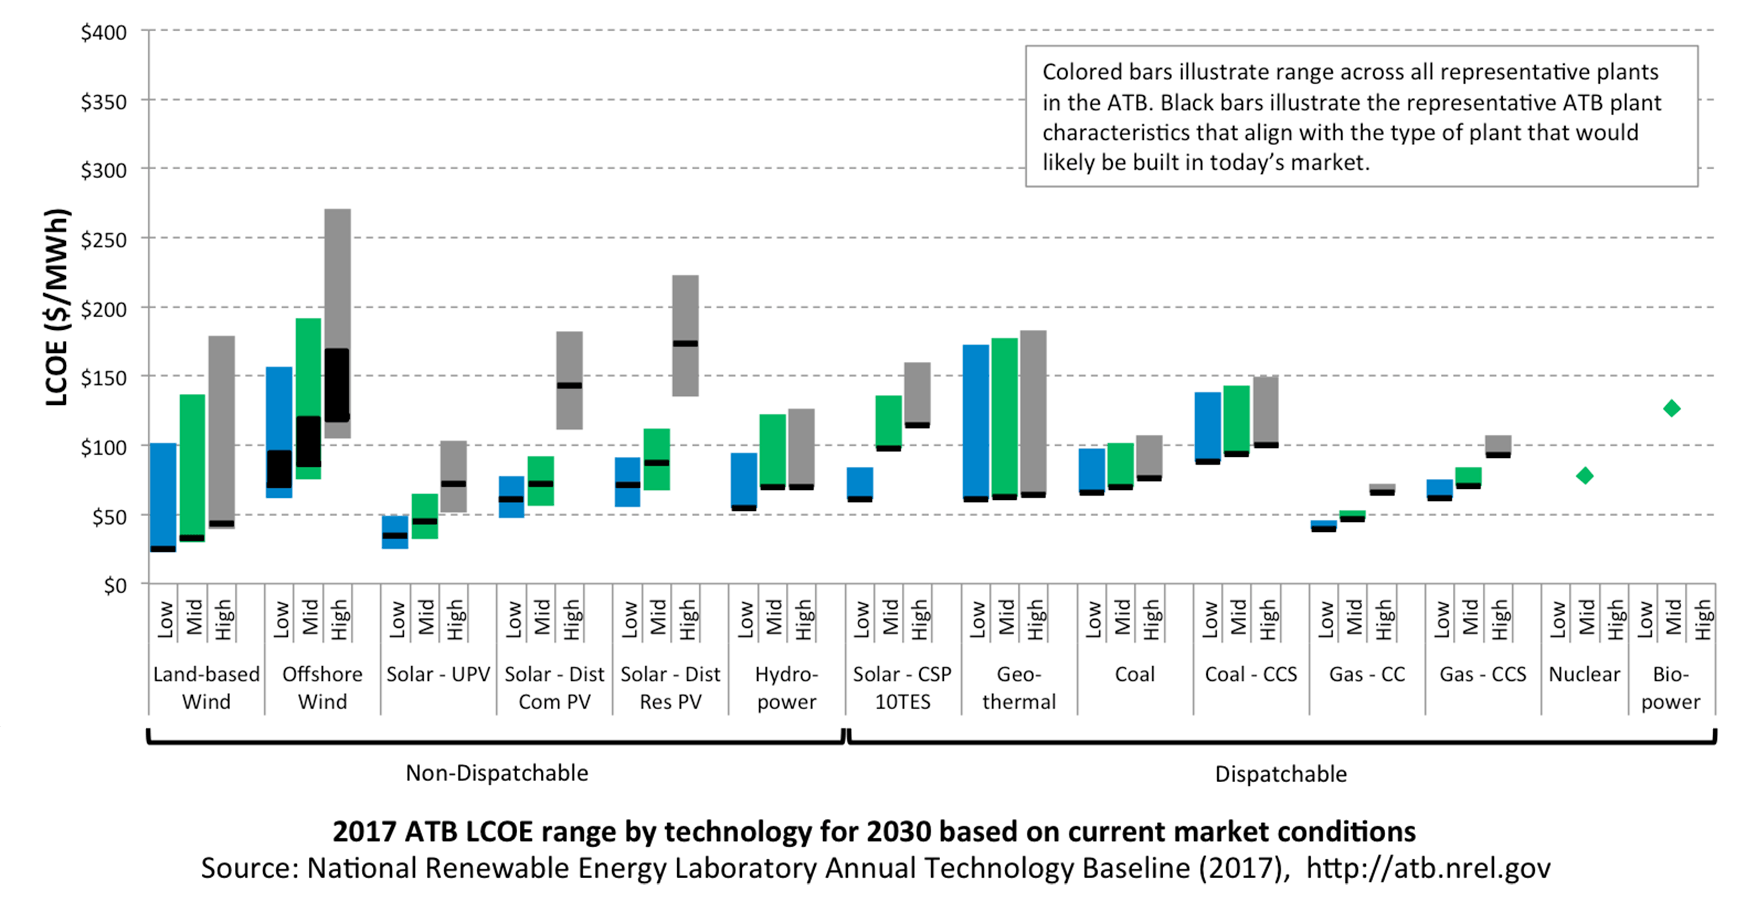
Graph titled 2017 ATB LCOE range by technology for 2030 based on current market conditions.
ATB LCOE range by technology for 2030 based on current market conditions.
Levelized cost of energy LCOE values calculated using macro-economic indicators (e.g., interest rates) estimated for 2017 in the U.S. Energy Information Administration’s Annual Energy Outlook 2017. The ATB focuses on electricity generation technology capital cost, operating costs, and energy production. It does not include time-varying macro-economic indicators. Values shown in 2015 U.S. dollars; hydropower is classified as non-dispatchable because most new hydropower generation would operate in run-of-river mode. LCOE captures the energy component of electric system planning and operation, but the electric system also requires capacity and flexibility services, typically associated with dispatchability, to operate reliably.

The ATB synthesizes current and projected data from various sources into a highly accessible and widely referenced resource for energy analysts. The 2017 ATB is available in a new interactive website at atb.nrel.gov and will be featured in a webinar on August 29.

“In addition to aggregating the most reliable, timely cost and performance data spanning the full range of energy technologies, the Annual Technology Baseline highlights key trends and makes projections out to 2050,” said NREL Senior Analyst Maureen Hand. “For energy analysts and others tasked with communicating relevant electricity technology cost and performance trends that have a bearing on energy markets, the ATB serves as an indispensable go-to resource that greatly facilitates and streamlines the work involved.”

For example, the ATB illustrates how solar photovoltaic (PV) capital costs have declined recently and are projected to continue to decline.  Similarly, land-based wind capital costs have fallen while capacity factors have increased. These are trends that are both projected to continue and make wind increasingly competitive with new generation from natural gas combined cycle plants in the near term.  The ATB provides three different levels of future technology cost and performance through 2050 to support analysis of future U.S. electric sector scenarios.

The ATB, which is supported by the Energy Department's Office of Energy Efficiency and Renewable Energy, incorporates NREL analysis, data from the U.S. Energy Information Administration, and information from a variety of published reports into two primary products for energy analysts. The Annual Technology Baseline spreadsheet documents detailed current and projected cost and performance data for electricity generation technologies. This year, a new interactive website describes each of the technologies and provides additional context for their treatment in the workbook. For each technology, the website provides:

  • Historical trends, current estimates, and future projections of three primary cost and performance factors: capital expenditures, capacity factor, and operations and maintenance cost
  • Documentation of the methodology and assumptions used to develop the projections of future cost and performance under high-, mid-, and low-cost cases
  • A calculated levelized cost of energy to illustrate the combined effect of the primary cost and performance factors.
The Annual Technology Baseline, which is supported by hundreds of literature citations, will be highlighted in a webinar on August 29, at 11 a.m.–1 p.m. MDT (1-3 p.m. EDT). Presenters will describe analytical products in detail, share examples of how they have been used, and provide an opportunity for attendees to ask questions. Register for the webinar at https://attendee.gotowebinar.com/register/4954393182456811522.

Friday, August 18, 2017

The climate and air-quality benefits of wind and solar power in the United States | Nature Energy

Abstract:
Wind and solar energy reduce combustion-based electricity generation and provide air-quality and greenhouse gas emission benefits. These benefits vary dramatically by region and over time. From 2007 to 2015, solar and wind power deployment increased rapidly while regulatory changes and fossil fuel price changes led to steep cuts in overall power-sector emissions. Here we evaluate how wind and solar climate and air-quality benefits evolved during this time period. We find cumulative wind and solar air-quality benefits of 2015 US$29.7–112.8 billion mostly from 3,000 to 12,700 avoided premature mortalities, and cumulative climate benefits of 2015 US$5.3–106.8 billion. The ranges span results across a suite of air-quality and health impact models and social cost of carbon estimates. We find that binding cap-and-trade pollutant markets may reduce these cumulative benefits by up to 16%. In 2015, based on central estimates, combined marginal benefits equal 7.3 ¢ kWh−1 (wind) and 4.0 ¢ kWh−1 (solar).

A free version of the paper dated January 2017 is currently available at https://emp.lbl.gov/sites/default/files/health_and_environmental_benefits_wind_solar_2007-2015_jan2017.pdf
by Dev Millstein, Ryan Wiser, Mark Bolinger & Galen Barbose
Nature Energy https://www.nature.com
Nature Energy 6, Article number: 17134 (2017); Published online: 14 August 2017

Wednesday, August 9, 2017

Wind Technologies Market Report

Report Highlights
The U.S. Department of Energy (DOE)’s Wind Technologies Market Report provides an annual overview of trends in the U.S. wind power market. You can find the report, a presentation, and a data file on the Files tab, below. Additionally, several data visualizations are available in the Data Visualizations tab. Highlights of this year’s report include:

Wind power additions continued at a rapid clip in 2016: $13 billion was invested in new wind power plants in 2016. In 2016, wind energy contributed 5.6% of the nation’s electricity supply, more than 10% of total electricity generation in fourteen states, and 29% to 37% in three of those states—Iowa, South Dakota, and Kansas.

Bigger turbines are enhancing wind project performance: Increased blade lengths, in particular, have dramatically increased wind project capacity factors, one measure of project performance. For example, the average 2016 capacity factor among projects built in 2014 and 2015 was 42.6%, compared to an average of 32.1% among projects built from 2004 to 2011 and 25.4% among projects built from 1998 to 2001.

Low wind turbine pricing continues to push down installed project costs: Wind turbine prices have fallen from their highs in 2008, to $800–$1,100/kW. Overall, the average installed cost of wind projects in 2016 was $1,590/kW, down $780/kW from the peak in 2009 and 2010. 

Wind energy prices remain low: After topping out at nearly 7¢/kWh for power purchase agreements (PPAs) executed in 2009, the national average price of wind PPAs has dropped to around 2¢/kWh—though this nationwide average is dominated by projects that hail from the lowest-priced Interior region of the country (such as Texas, Iowa, Oklahoma). These prices, which are possible in part due to federal tax support, compare favorably to the projected future fuel costs of gas-fired generation. 
Installed Cost Of Wind Has Declined Since 2009-2010

The supply chain continued to adjust to swings in domestic demand for wind equipment: Wind sector employment reached a new high of more than 101,000 full-time workers at the end of 2016. For wind projects recently installed in the U.S., domestically manufactured content is highest for nacelle assembly (>90%), towers (65-80%), and blades and hubs (50-70%), but is much lower (<20%) for most components internal to the turbine.

Continued strong growth in wind capacity is anticipated in the near term: With federal tax incentives still available, though declining, various forecasts for the domestic market show expected wind power capacity additions averaging more than 9,000 MW/year from 2017 to 2020.

PDF icon Report PDF3.24

Lawrence Livermore Berkeley Lab Electricity Markets and Policy Group https://emp.lbl.gov

Saturday, August 5, 2017

The Price of Climate Deregulation: Adding Up the Costs and Benefits of Federal Greenhouse Gas Emission Standards

Federal climate regulations are currently under attack, in part due to the perception that these regulations will impose excessive costs on regulated industries and society as a whole. But according to federal projections, the benefits of these regulations would significantly outweigh the costs. In a new paper, we added up the projected economic impacts of major federal rules aimed at reducing greenhouse gas emissions and found that the net benefits could reach nearly $300 billion per year by 2030. The rules will also generate a variety of non-monetized benefits, such as improved public health outcomes and the creation of jobs, as well as climate mitigation benefits that will extend well beyond 2030.

Jessica Wentz and Nadra Rahman analyzed the projected economic impacts of major regulations aimed at controlling carbon dioxide and methane: U.S. EPA’s Clean Power Plan, the Bureau of Land Management’s Methane and Waste Prevention Rule, EPA’s 2016 New Source Performance Standards for the oil and gas sector, and EPA’s emissions standards for both light-duty and heavy-duty vehicles.

Rahman and Wentz primarily aggregated EPA and Interior’s own cost-benefit projections of the Obama-era regulations. They also compared the values to separate cost-benefit analyses developed by independent researchers, a number of whom challenged the agencies’ analyses of the regulations, alternately stating that EPA and BLM had overestimated benefits or underestimated costs.
The $370 billion in gross benefits includes the positive impacts of reducing 980 million metric tons of carbon dioxide equivalent by 2030, along with the health benefits of also reducing other pollutants, such as nitrogen oxides.

These benefits would be four times greater than the projected $84 billion in total costs of implementing major regulations crafted under the Obama administration, said researchers in a paper published on the center’s website yesterday.

On a year-to-year basis, the economic benefits can either significantly exceed, or at the very least match, the cost of implementation. Some of the highest potential benefits come from implementing the Clean Power Plan and from standards for medium- to heavy-duty vehicles. The total does not include other benefits like job creation and long-term climate change mitigation benefits.

Clean Power Plan
Based on EPA’s estimates, the net economic benefits of the rule could be around $7 billion in 2020, and then rise to $46 billion in 2030.  These figures included: compliance costs, an estimated reduction of 74 million metric tons of CO2 emissions in 2020 and a reduction of 375 million metric tons in 2030. The dollar values also counted health benefits resulting from the reduction of other pollutants like sulfur dioxide and nitrogen oxides. The economic benefits don’t include other potential positives of the rule like avoided premature deaths, lower exposure to hazardous air pollutants and impacts on ecosystems.

The researchers note that the economic benefits are calculated using a social cost of carbon, a complex metric that puts a dollar value on the emission of 1 ton of carbon. The value takes into account how rising global temperatures will affect the planet and society. In the president’s “energy independence” executive order, Trump signaled that the administration would seek to alter this method of calculating the costs of climate change, though agencies could use a related metric that would only take into account domestic impacts of climate change.

Motor Vehicle Emissions
Light-duty vehicles: The fuel efficiency improvements alone for light-duty vehicles are enough to offset the costs of implementing rules on emissions from these vehicles, according to the EPA figures the researchers cited. The net economic benefits of fuel efficiency standards for model years 2012 to 2016 are expected to be $34.7 billion in 2020 and $100.4 billion in 2030. Meanwhile, standards for model years 2017 through 2025 could lead to net benefits of $168 billion in 2020 and $81.4 billion in 2030. Medium and heavy-duty vehicles: According to EPA data, phase one of emissions standards for these vehicles, for model years 2014 to 2018, could lead to net benefits of $10 billion in 2020 and $27.3 billion in 2030. Phase two, for model years 2019 to 2028, could have net benefits of $31.5 billion in 2020 and $74.4 billion in 2030.

New Source Performance Standards for the Oil and Gas Sector
As with the Clean Power Plan, EPA used the social cost of carbon metric to calculate the net monetary benefits of controlling methane, volatile organic compounds and toxic air pollutants emitted from new and modified sources. The net benefits of the rule could be $37 million by 2020 and go up to $180 million in 2025. These numbers consider compliance costs and methane emissions reductions of 300,000 short tons in 2020 and 510,000 short tons in 2025. Not all benefits were included. EPA did not put a dollar value on the health benefits of potential reductions in ozone, which is formed from volatile organic compounds. Estimates also did not include potential natural gas savings from captured methane.
...

By Nadra Rahman and Jessica Wentz
August 3rd, 2017       

Friday, August 4, 2017

If we keep subsidizing wind, will the cost of wind energy go down? [ The Conversation

As more wind turbines have been put in place, the cost of wind energy has gone down

There are high hopes for renewable energy to help society by providing a more stable climate, better energy security and less pollution. Government actions reflect these hopes through policies to promote renewable energy. In the U.S. since 1992 there’s been a federal subsidy to promote wind energy, and many states require electricity utilities to use some renewable energy.

But when is the right time to stop government support for an energy technology?

This is a timely question: Rick Perry’s Department of Energy is currently working on a grid reliability report that many expect to argue that wind and solar cause reliability problems because they don’t supply power continually. A conclusion like this can be used to justify removal of government subsidies or regulations favoring other sources of energy.

Subsidies need not last forever – there can come a time when its objective has been achieved or experience suggests the subsidy is not working as intended.

Is it time to end subsidies for wind? A big part of the answer to this question lies in whether subsidies are actually making wind cheaper.

Why subsidize energy technology

The justification for subsidizing a given technology is that it delivers public benefits that outweigh the subsidy cost. If a technology shows promise to become cheap enough, the subsidy can be viewed as a temporary stimulus to bring it a point where it can stand on its own.

For example, in the early days of the semiconductor industry, integrated circuits were too expensive for consumer markets. Government demand for military applications provided a critical bridge to bring down costs and activate broader markets.

On the other hand, subsidizing an emerging technology that has trouble bringing down costs may be inefficient. For decades, the U.S. government has subsidized or mandated production of corn ethanol. Yet ethanol is still not market-competitive, at least not with recent crude oil prices.

Wind power’s ‘learning curve’

The price for wind power has gone down over the years, but how cheap is it getting? There is a surprisingly diverse set of answers to this question. There are over 100 existing studies of wind cost trends, with results ranging from wind power becoming more expensive over time to becoming cheaper so quickly that it will soon be cheaper than fossil fuels. Curiously enough, while researchers have recently started to note disparities between studies, no one has yet grappled with explaining and reducing such variability. This is, unfortunately, a common situation in many research domains: Various groups get conflicting results from similar analyses, but no one works on understanding why these differences arise.

In a recent paper, we sought to better understand cost reductions in wind power by finding patterns in historical trends.

Wind costs follow what economists call a learning curve: For every doubling of wind production, the cost goes down by a fixed percentage. For example, if the price of electricity from wind is 10 cents per kilowatt-hour with a given number of wind farms, a 10 percent “learning rate” means that wind electricity would cost 10 percent less, or 9 cents per kilowatt-hour, if one doubles the number of wind farms.


Our main finding was that the learning rate for wind power is in the range of 7.7 percent to 11 percent. That means if more wind power is installed and the cost of energy continues to decline as it has in recent years, the cost of generating electricity with wind will fall from 5.5 cents/kilowatt-hour today to 4.1–4.5 cents/kilowatt-hour in 2030.

Previous studies obtained learning rates from -3 percent to +33 percent, the minus sign indicating wind becoming more, rather than less, expensive over time. Why are the results so different? We showed that one can get very different outcomes depending on the method and data range used.

First, we believe it is important to account for wind power costs in terms of the total cost to generate electricity. Many prior studies measured wind cost as the price to build the capacity to make electricity at peak wind times. But this is a poor measure because much of the progress in wind technology in recent years has been to generate more power when the wind is weaker.
https://www.flickr.com/photos/130749842@N07/16328618272/
Secondly, it is important to treat wind power as a global industry. The adoption of wind in one country helps the industry develop and grow so that wind becomes cheaper in other countries. Modeling wind adoption in only one nation can skew results.

Finally, results depend strongly on the date range of data used. Even with an identical method, the estimated learning rate can change up to 10 percent depending on which years of data you use.

To subsidize or not to subsidize?

So if wind costs will fall to 4.1–4.5 cents/kilowatt-hour in 2030, as we found, what does this mean for wind subsidies? The U.S. Energy Information Agency projects the cost of natural gas and coal power in 2030 will be 4.5 and 5 cents per kilowatt-hour respectively. Taking these numbers at face value, wind is on track to become cheaper than fossil fuels as a source of electricity.

Friday, July 28, 2017

States Can Save Consumers and Businesses $113B with New Appliance Standards | ACEEE

States could save consumers and businesses $113 billion by adopting new efficiency standards for products such as computers and faucets, according to a new report, States Go First: How States Can Save Consumers Money, Reduce Energy and Water Waste, and Protect the Environment with New Appliance Standards, released July 25, 2017 by the Appliance Standards Awareness Project (ASAP) and the American Council for an Energy-Efficient Economy (ACEEE). The report recommends 21 appliance standards that states can adopt in the near term.

“These standards give states a great opportunity to save energy and water, lower utility bills for consumers and businesses, and reduce air pollutant emissions,” said Joanna Mauer, technical advocacy manager of ASAP and lead author of the report. “By adopting new appliance standards, states can also boost local economies and reduce strain on the electric grid.”
...

The 21 recommended standards in the report cover a wide range of energy- and water-using residential and commercial products. They include computers and monitors, commercial dishwashers, faucets, and portable air conditioners. The report estimates potential savings through 2035 assuming that the standards would take effect in 2020. On a national level, the report found that the 21 recommended standards could:
  • Provide $113 billion in net present value savings for consumers and businesses, taking into account both utility bill savings and estimated impacts on product costs for items sold between 2020 and 2035
  • Save 41 billion kilowatt-hours of electricity annually in 2035, or about 1.5% of current total residential and commercial annual electricity use
  • Save 155 trillion Btus of natural gas annually in 2035, or about 2% of current total residential and commercial annual natural gas use
  • Save 630 billion gallons of water annually in 2035, or about 6% of current annual residential water usage
  • Reduce annual CO2 emissions in 2035 by 23 MMT, which is equivalent to the annual CO2 emissions of about seven average coal-fired power plants
Other key findings include:
  • The top three products in terms of potential economic savings are water-using products: faucets, showerheads, and lawn spray sprinklers.
  • More than half of the total potential primary energy savings come from the recommended standards for faucets, high color rendering index (CRI) fluorescent lamps, and computers and monitors.
  • The average US household could save $106 annually on its energy and water bills from the recommended standards in 2035. The potential savings vary from $72 per average household in Iowa to $215 in Hawaii.
  • The US energy and water bill savings over the useful life of the 21 products outweigh the estimated additional costs by a factor of more than 7; in every state, these potential savings outweigh the costs by a factor of more than 4.
Most of the recommended standards in the report are based on standards that already exist in at least one state or ENERGY STAR® or WaterSense specifications. Three of the standards are for products for which final federal standards have been put on hold by the Trump administration.
At least 18 states have enacted appliance standards at various times. Most of today’s national standards, which cover products ranging from refrigerators to commercial air conditioners to electric motors, started out at the state level.

“State standards have not only provided benefits to states adopting standards, but have also helped spur national standards,” said Steven Nadel, executive director of ACEEE. “Even when just a small number of states adopt standards, it can be sufficient to affect national markets.”

The full report is available at: http://aceee.org/research-report/a1702

State-by-state savings estimates for each of the 21 recommended standards are available at: https://appliance-standards.org/state-savings-state-standards

ASAP (appliance-standards.org) organizes and leads a broad-based coalition effort that works to advance, win, and defend new appliance, equipment, and lighting standards that deliver large energy and water savings, monetary savings, and environmental benefits. Working together, the ASAP coalition supports new and updated standards at the national and state levels through technical and policy advocacy and through outreach and education. 

The American Council for an Energy-Efficient Economy acts as a catalyst to advance energy efficiency policies, programs, technologies, investments, and behaviors.

The American Council for an Energy-Efficient Economy ACEEE http://aceee.org
Press Release dated July 25, 2017

Monday, July 24, 2017

What Is the Cost of a Renewable Energy–Based Approach to Greenhouse Gas Mitigation?

Abstract
Energy policies for greenhouse gas (GHG) mitigation in the United States have set sector-specific standards, such as the Renewable Fuel Standard (RFS) and the Renewable Portfolio Standard (RPS) for the transportation and the electricity sectors, respectively. This paper examines the welfare costs and effectiveness of GHG abatement with these policies and compares them with those under a carbon tax normalized to achieve the same level of abatement over the 2007–2030 period. We show that the global welfare cost per ton of GHG abatement with the RFS and RPS is $171, while with the carbon tax it is $7.

Map of States with Renewable Energy Portfolio Standards

by Anthony Oliver, and Madhu Khanna
Land Economics http://le.uwpress.org via University of Wisconsin Press
August 1, 2017; Volume 93, Number 3; Pages 437-458

Friday, June 30, 2017

Estimating economic damage from climate change in the United States | Science

Abstract:
Estimates of climate change damage are central to the design of climate policies. Here, we develop a flexible architecture for computing damages that integrates climate science, econometric analyses, and process models. We use this approach to construct spatially explicit, probabilistic, and empirically derived estimates of economic damage in the United States from climate change. The combined value of market and nonmarket damage across analyzed sectors—agriculture, crime, coastal storms, energy, human mortality, and labor—increases quadratically in global mean temperature, costing roughly 1.2% of gross domestic product per +1°C on average. Importantly, risk is distributed unequally across locations, generating a large transfer of value northward and westward that increases economic inequality. By the late 21st century, the poorest third of counties are projected to experience damages between 2 and 20% of county income (90% chance) under business-as-usual emissions (Representative Concentration Pathway 8.5).
File:IdeJCTerrebonneGustavApricotHouse1.jpg
https://en.wikipedia.org/wiki/Isle_de_Jean_Charles,_Louisiana
by Solomon Hsiang 1,2,*,†, Robert Kopp 3,*,†, Amir Jina 4,†, James Rising 1,5,†, Michael Delgado 6, Shashank Mohan 6, D. J. Rasmussen 7, Robert Muir-Wood 8, Paul Wilson 8, Michael Oppenheimer 7,9, Kate Larsen 6, and Trevor Houser 6
1. Global Policy Laboratory, Goldman School of Public Policy, University of California, Berkeley, CA, USA.
2. National Bureau of Economic Research, Cambridge, MA, USA.
3. Department of Earth and Planetary Sciences and Institute of Earth, Ocean, and Atmospheric Sciences, Rutgers University, New Brunswick, NJ, USA.
4. Department of Economics and Harris School of Public Policy, University of Chicago, Chicago, IL, USA.
5. Energy Resource Group, University of California, Berkeley, CA, USA.
6. Rhodium Group, New York, NY, USA.
7. Woodrow Wilson School of Public and International Affairs, Princeton University, Princeton, NJ, USA.
8 Risk Management Solutions, Newark, CA, USA.
9 Department of Geosciences, Princeton University, Princeton, NJ, USA.
* Corresponding author. Email: shsiang@berkeley.edu (S.H.); robert.kopp@rutgers.edu (R.K.)
Science  http://science.sciencemag.org 30 Jun 2017:
Volume 356, Issue 6345, pp. 1362-1369